CHOICE (Custom Health Option and Individual Care Expense Arrangement), formerly known as ICHRA
A CHOICE Arrangement allows employers to reimburse employees for individual health insurance premiums and eligible out-of-pocket medical expenses incurred by employees or their dependents during the plan year.
Our CHOICE solution offers a flexible and cost-effective alternative to traditional group benefits
CHOICEs can be cost-effective and flexible for employers, their employees and their dependents. This is an exciting win for employers of all sizes that want to remain competitive and promote retention of their valuable employees!
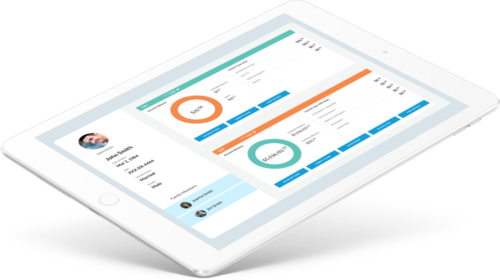
Step 1: Employer Sets Up CHOICE
A CHOICE allows employers to reimburse their employees for individual health insurance premiums and eligible out-of-pocket medical expenses they or their dependents may incur during the plan year. A CHOICE requires less overhead than traditional group benefits and can be a cost effective way to offer your employees more choice when it comes to their health benefits.
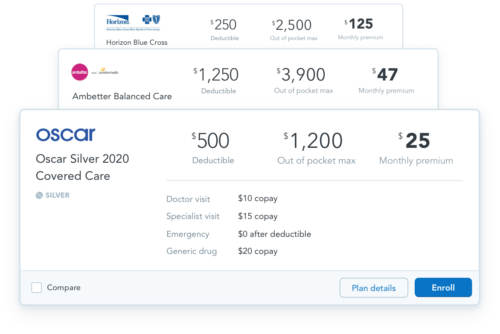
Step 2: Employees Purchase Individual Plans
We understand that finding the right health insurance plan may feel like a daunting task. Our platform makes shopping for an individual insurance plan, enrolling in a plan and managing the employees coverage super easy. Our one-stop solution provides integrated online enrollment and support tools that helps CHOICE-eligible employees find quality, affordable health insurance. This employee plan shopping, enrollment and support experience is included as part of our holistic “CHOICE Plus” solution offering.
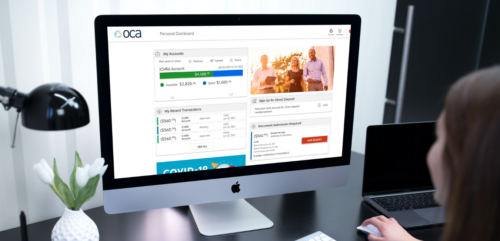
Step 3. Employee Pays Premium Using CHOICE Funding
CHOICEs are based on reimbursing employees for their insurance premium rather than buying it for them. This means employees can use our OCA issued debit card to pay for individual health insurance premiums and/or eligible medical expenses (depending on the CHOICE plan design) or pay with their personal funds and submit a claim for reimbursement. Employees will be able to easily access, submit, and track all reimbursements through our member portal/mobile app!
CHOICEs can be a innovative solution for employer groups of all sizes!

Benefit Cost Control
CHOICEs allow for better cost control allowing employers to define their benefit budget and control health benefit costs.

Customization & Flexibility
CHOICEs give employers the flexibility to design a benefits plan that meets their specific business needs.

Employee Personalization
With a CHOICE, employees own their health insurance coverage, are provided more choice and decision support to find the best plan that meets their budget and healthcare needs.
Plan Portability
Employees own their health insurance coverage, which means they can take it with them if they change jobs
Tax-free Benefit
Employers can deduct the CHOICE amount of their contributions. Since the account is funded on a notional basis, the employer can take the deduction only when the amounts are actually paid out.
Improved Client Satisfaction
A CHOICE requires less overhead than traditional group benefits and can be a cost effective way to offer employees more choice when it comes to their health benefits.
Accessing the Appetite for CHOICEs
CHOICEs can allow for more predictable spending, as the costs are up front and can be scaled for part-time employees. These plans work especially well for smaller employers who can’t afford to offer traditional group plans, as well as big employers with many part-time workers.
Schedule DemoCHOICE Concierge Services
Our team of Health Assistants help employees navigate the complexities of the healthcare system while saving them time, money, and frustration. We can help with negotiation of confusing bills, finding the highest quality in-network doctors, compare treatment costs for services, explain benefits in plain language, provide support during open enrollment, and much more! Our goal is to ensure that members get the most of their benefits and their benefit dollars by guiding them to make better decisions. Our concierge-style approach saves members time, money, and hassle.
Learn More
Generate CHOICE Annual Notice
Within minutes, by clicking the link below you can generate an CHOICE Annual Notice which is required to be distributed to CHOICE eligible employees before the beginning of each plan year.
CHOICE Affordability Calculator
We created this calculator to help you understand what CHOICE contributions are necessary to meet the Affordable Care Act’s affordability thresholds for employers with more than 50 full-time employees.

Confirm Employee Affordability
Click the link below to estimate health insurance premiums and subsidies for an individual. You can enter the employees income, age, and family size to estimate their eligibility for subsidies and how much they could spend on health insurance.
CHOICE Frequently Asked Questions
How does a CHOICE differ from an HRA?
A CHOICE can reimburse individual insurance premiums, while a traditional HRA cannot. In addition, a traditional HRA must be integrated with a group health insurance plan, whereas a CHOICE works with individual insurance plans.
What are the requirements for an HRA to qualify as a CHOICE?
1. You may not offer the same class of employees a choice between a CHOICE and a traditional group coverage health insurance plan.
2. You can leverage 10 different employee classes to structure benefit eligibility and allowance amounts. While different terms may apply to different classes of employees, the same terms must be offered to all employees within the same class.
3. Participating employees and dependents must be enrolled in an individual health insurance plan or Medicare to participate in a CHOICE.
4. You must have reasonable procedures in place to verify employee enrollment in an individual health insurance plan or Medicare.
5. A written notice must be provided to eligible employees at least 90 days prior to the beginning of the plan year explaining key terms of the CHOICE.
6. Eligible employees must have the option to opt out annually and upon termination.
What are the employee classes?
You can choose to create different reimbursement rules for different types of employees, referred to as employee classes, allowing you to fine tune your CHOICE offering. Permitted employee classes include:
• Full-time employees
• Part-time employees
• Seasonal employees
• Employees covered by a collective bargaining agreement
• Employees in a waiting period for coverage
• Salaried employees
• Hourly employees
• Temporary employees of staffing firms
• Non-resident aliens with no U.S.-based income
• Employees in the same geographic location
• A combination of two or more of the above
Are there minimum class size requirements?
If you offer a traditional group health insurance plan to at least one class of employees and a CHOICE to another class of employees, minimum size requirements apply to the following classes:
• Salaried employees
• Hourly employees
• Full-time employees
• Part-time employees
• Employees in the same geographic location
For employers with fewer than 100 employees, the class must be at least 10 employees. For employers with 100 to 200 employees, the class must be at least 10 percent of the employees. For employers with more than 200 employees, the class must be at least 20 employees.
Are there minimum participation requirements?
With the CHOICE, there are no participation requirements. If employees decide not to use the benefit, there is no cost concern for the plan.
Can employers offer a CHOICE and a traditional group health insurance plan?
Yes. Employers may offer a CHOICE and a traditional group health insurance plan as long as employees in each class are only offered one solution and certain classes being offered reimbursement through a CHOICE meet minimum class size requirements.
What is the tax benefit for me as an employer?
Employers can deduct the amount of their contributions. Since the account is funded on a notional basis, the employer can take the deduction only when the amounts are actually paid out.
Is there a tax benefit for my employees?
Yes. CHOICE funds are contributed to employees on a pre-tax basis; therefore, disbursements are not included when calculating taxable income. For this reason, employees can not claim an income tax deduction for an expense that has been reimbursed under the CHOICE.
What happens to the funds if my employee leaves the company?
CHOICE funds are not portable. With the CHOICE, you have pledged to pay the funds if needed; therefore any unused funds remain with you, the employer.
How much can an employer contribute to employee CHOICEs?
There are no minimum or maximum contribution amounts for CHOICEs. Employers may contribute as much or as little as they would like as long as it’s offered fairly to each class.
Can employees contribute to an CHOICE?
No. Only employers may contribute funds to an CHOICE.